Do I Need a Money Transmitter License for My App?
Whether your app needs a money transmitter license depends on what it actually does with money — not what you call it. Here is how to determine if your specific product requires licensing.
Stay ahead of compliance trends, regulatory updates, and industry best practices curated for modern fintechs.
Whether your app needs a money transmitter license depends on what it actually does with money — not what you call it. Here is how to determine if your specific product requires licensing.
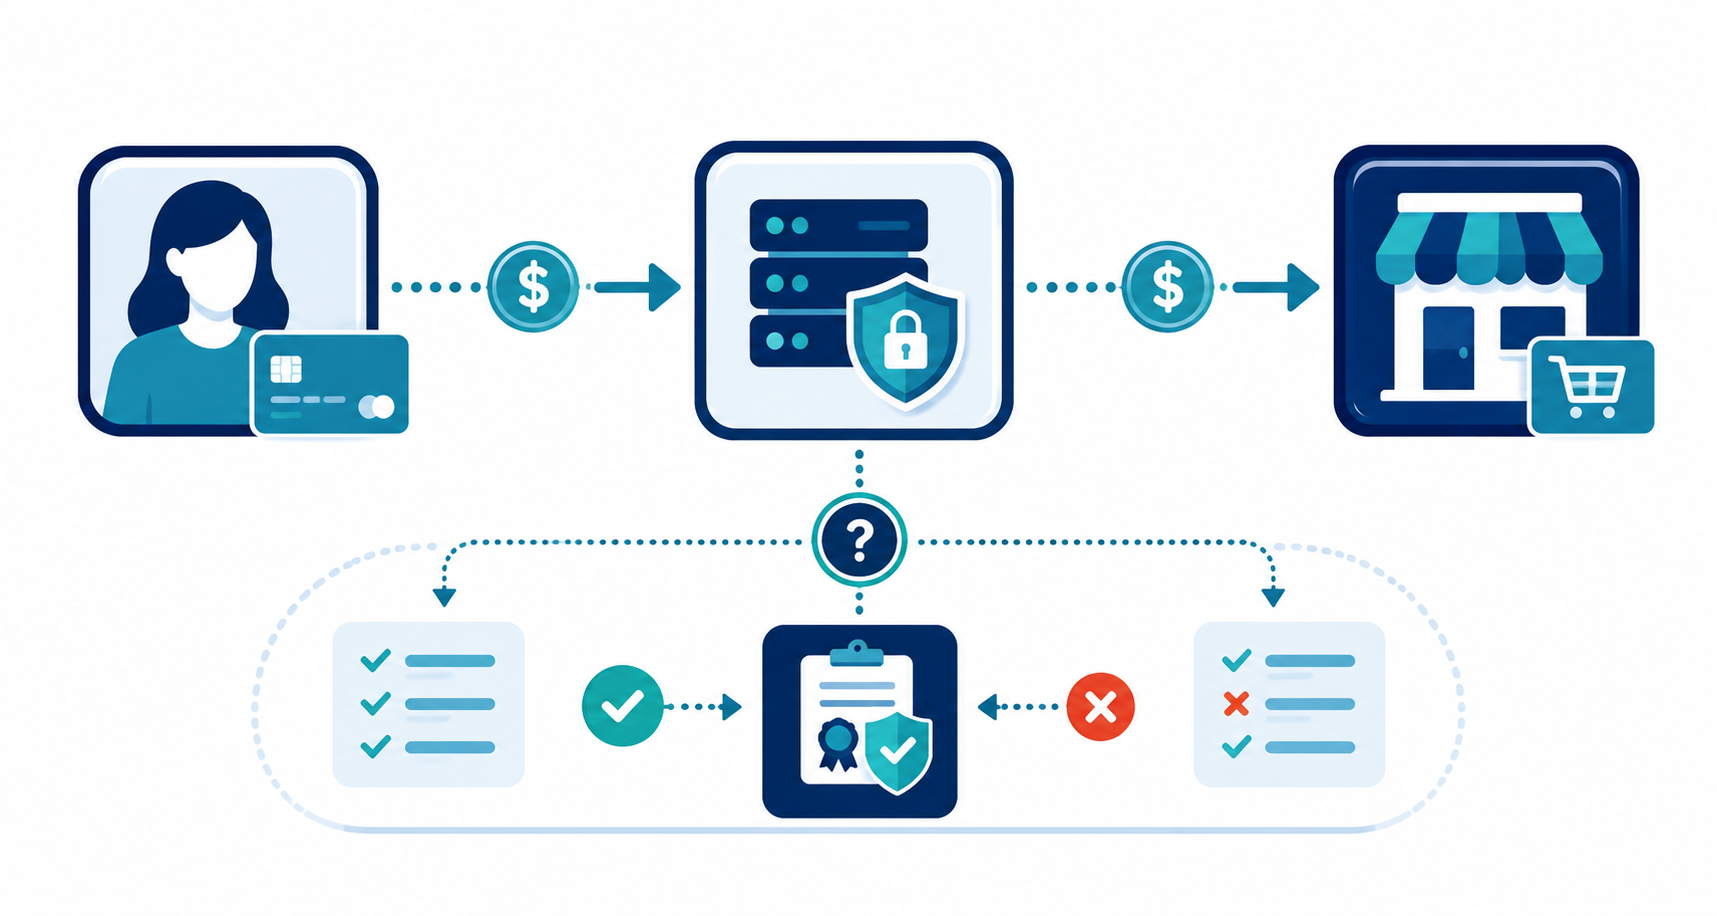
Whether a payment processor needs a money transmitter license depends on exactly how funds flow through the business. Here is how to determine your licensing requirement and what the payment processor exemption actually covers.
Compliance can feel overwhelming for early-stage fintechs. Here is a practical, no-jargon guide to where to start — what matters most at the earliest stage and how to build a foundation that scales.
Regulatory sandboxes allow fintechs to test innovative products with limited regulatory requirements for a defined period. Here is which U.S. states have sandbox programs, what they offer, and how to apply.
Money transmitter license costs vary dramatically by state. Here is a breakdown of application fees, surety bonds, net worth requirements, and total costs — plus how to budget for a national licensing program.
Remittance companies that send money across borders need state money transmitter licenses. Here is how the licensing process works for remittance businesses, what states require, and how to build a licensing strategy.
Most states require a surety bond as part of money transmitter licensing. Here is how bonding requirements work, what bond amounts look like state by state, and how your transaction volume affects what you pay.
Every Money Services Business must designate a compliance officer to manage its BSA/AML program. Here is what the compliance officer role requires, what qualifications to look for, and how the role differs at an MSB versus a bank.
Prepaid cards and digital accounts are subject to Regulation E consumer protection requirements. Here is what the prepaid account rules require, how they apply to fintech products, and what compliance looks like in practice.