Fintech Compliance
3 weeks ago
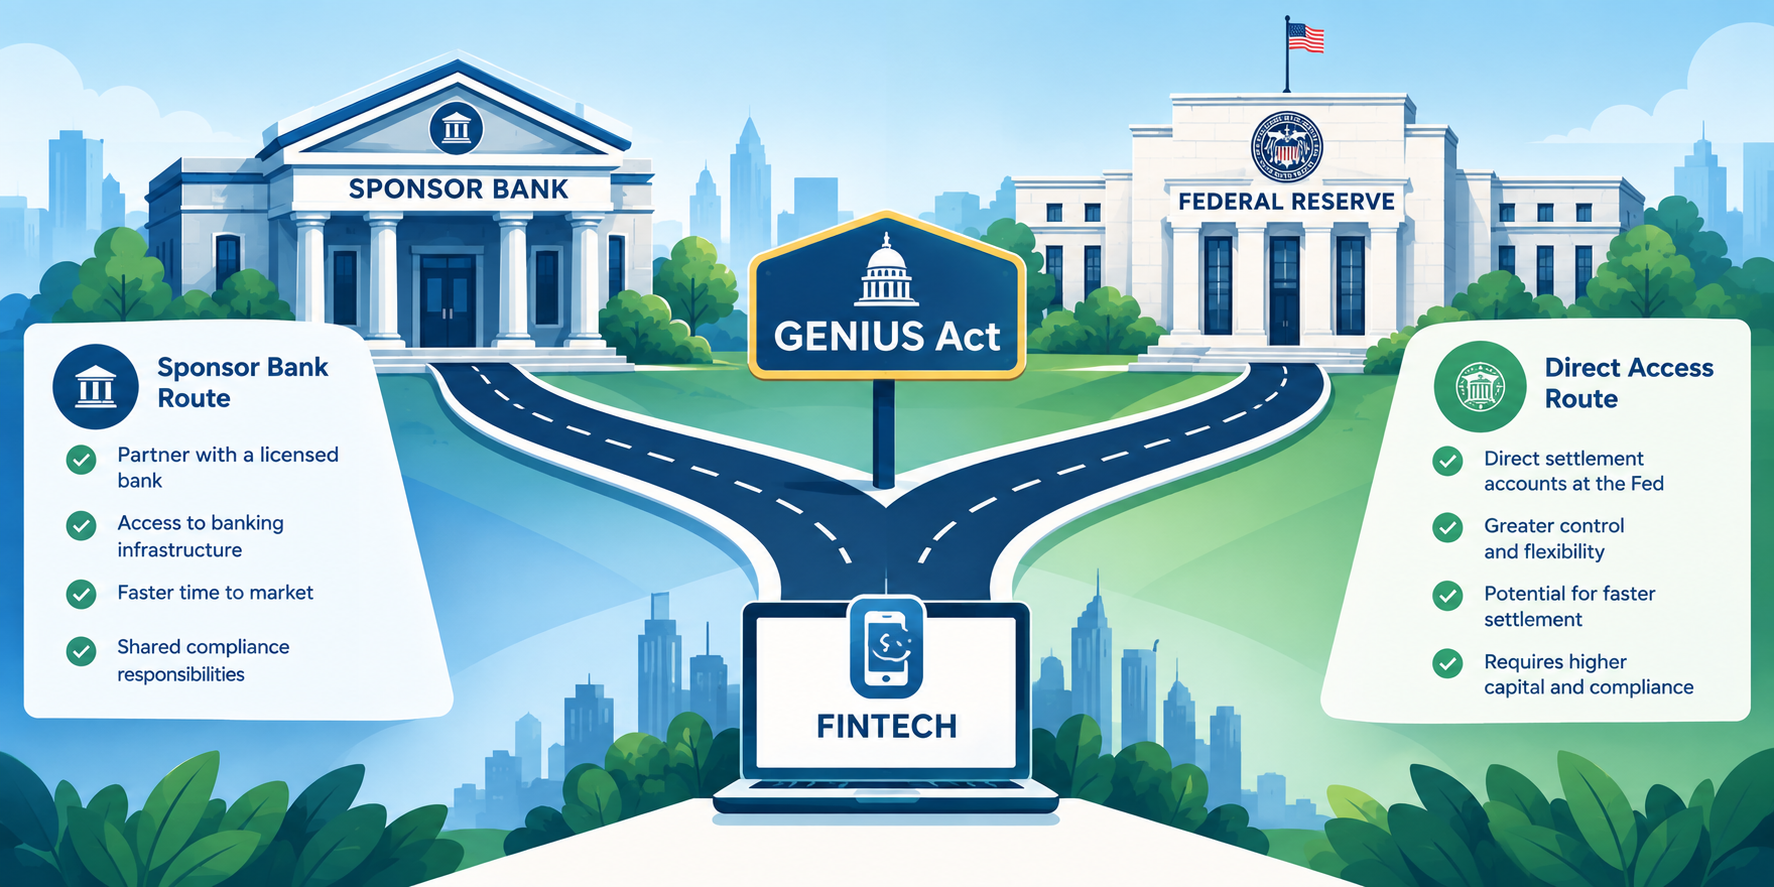
If Fintechs Get Direct Fed Access, What Happens to the Sponsor Bank Model?
The GENIUS Act is accelerating the question nobody in fintech wants to answer too early: if stablecoin issuers and non-bank fintechs get direct access to Federal Reserve payment rails, what happens to the sponsor bank relationships that currently underpin most of the industry?
Read article